News
 Google Wallet
 Makes Everyday Errands Easier, but Support Still Varies
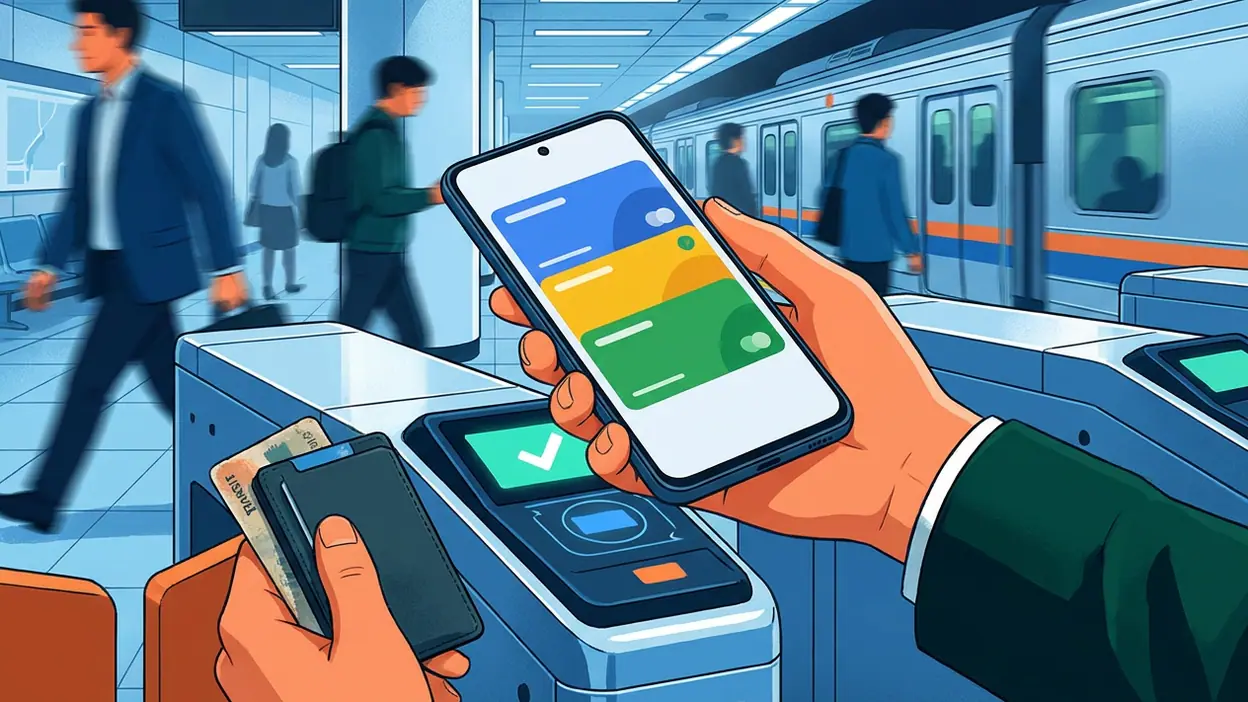
The moment that makes a digital wallet feel essential is rarely dramatic. It is a checkout line moving faster than your hands can find a card, a transit gate closing behind the person ahead, or a boarding pass buried in an inbox. Google Wallet is built for those small, increasingly common moments. Its case is not that a phone can replace everything in your pocket; it is that familiar daily credentials are becoming easier to use when they live together, ready for a tap.
That shift matters now because phone-based payment has moved from novelty to habit, while tickets, loyalty cards, passes, and—in some places—identity documents are following at different speeds. The app is most convincing when it quietly reduces rummaging. It is less convincing when people expect one universal digital wallet and discover that support still varies by country, issuer, device, and merchant.

Google Wallet
Google LLC4.3
The pocket is changing faster than the rules
For years, a wallet was a physical index of ordinary life: a payment card, a transit pass, a membership card, perhaps a folded receipt. The phone first displaced the camera and music player, then became the place where people check in, book travel, and prove they paid. Now it is also becoming the object they reach for at the counter. This is not a clean handover from leather to glass. It is a gradual transfer of the items people use most often.
The behavior shift is practical rather than ideological. People already carry phones everywhere and unlock them dozens of times a day. A payment card stored on that familiar device can be quicker than opening a bag, and contactless readers have made the interaction feel ordinary. A digital boarding pass or event ticket fits the same pattern: the phone is already in hand, so the credential is there when needed. The wallet app brings these moments into one recognizable place instead of leaving each one in a different email, retailer app, or screenshot.
Convenience here means fewer small interruptions, not a radically new way to spend. That distinction is important. A finance app can encourage more transactions by making spending frictionless, but Wallet’s strongest everyday value is organizational: keeping useful credentials within reach and reducing the chance of arriving at a gate or checkout with the wrong thing open.
Google Wallet feels timely because it meets this behavior without asking users to learn a complicated system. Add an eligible payment card, complete the bank’s verification, and the phone can be used at supported contactless terminals. Cards and passes can be added through supported issuers and services, and some items may be added from a website or confirmation email. The exact mix depends on where you live and which providers participate, but the basic idea is easy to grasp: store a digital version of something you already use, then bring it up when the real-world task arrives.
Payment is the immediate use case most people understand. After setup, paying at a contactless terminal usually takes less effort than opening a banking app and navigating to a payment screen. Depending on the Android device and settings, the wallet can be opened through a quick shortcut or used directly at the reader. That speed is most noticeable in small transactions, where a few seconds of fumbling feel disproportionate. It also helps when a card is tucked away or a bag is awkward to reach.
Travel and events make the second case. A rail pass, boarding pass, or admission ticket stored alongside payment cards can make a travel day feel less fragmented. Instead of switching among a browser, email, and an operator’s app, the relevant pass may be easier to find in the wallet. Some passes can provide useful updates, though the level of detail is not uniform. Wallet does not turn every transport system into a compatible one, and travelers should still check the operator’s rules before relying on a digital pass as their only copy.
Loyalty cards are another low-drama win. A digital membership card is easier to bring along than a plastic one used only a few times a month. It is also less likely to be forgotten at home. For a person who shops at several stores, keeps tickets for occasional events, and pays by phone, the appeal is cumulative: each saved card eliminates one more reason to keep a bulging physical wallet. A paper receipt or a card from an unsupported local business may still have to stay in the old stack.
The people adopting this kind of utility fastest are likely to be frequent phone payers and commuters, followed by travelers, students, and anyone who regularly visits businesses with loyalty programs. They already rely on a phone for navigation, messaging, and check-in, so a digital credential feels like a natural extension rather than a new ritual. People who share devices, prefer cash, use older hardware, or need services not supported in their region have less reason to switch quickly. The trend is broad, but adoption remains uneven.
Compared with older options, the useful difference is consolidation. A bank’s app may handle payments for that bank’s customers; a transit operator’s app may handle a particular route; a retailer’s app may keep one loyalty account. Wallet can collect compatible items from several of those sources in a common interface. That does not make it a replacement for the apps that issue the tickets or manage the accounts. It makes it a convenient shelf for the credentials those services provide.
That distinction also keeps expectations in check. Wallet is not a universal pass for every payment terminal, airline, transit network, or identity checkpoint. Card support depends on the issuing bank and country, and digital ID availability is limited to specific jurisdictions and uses. Some merchants still prefer physical cards or have terminals that do not cooperate. An Android phone also needs to be charged and kept secure; if it dies, the digital versions go with it. Keeping a backup payment method remains sensible.
The interface is generally straightforward, but the experience can feel uneven around the edges. Adding an item may send the user through another company’s sign-in or verification flow. A pass can be easy to find in one service and awkwardly absent from another. Features vary across devices and regions, and the name itself can be confused with Google Pay, the company’s payment brand and service. Most users will not care about that distinction until a specific feature or card behaves differently than expected.
There is also a privacy question worth treating plainly. A phone wallet handles sensitive financial credentials, so security is not a decorative extra. Payment tokens are designed to avoid exposing the actual card number to the merchant during a tap, and device locks add a barrier if the phone is lost. Still, users should protect their screen lock, know how to secure a missing device, and understand what information a particular pass shares. Digital storage reduces some physical risks but creates others, especially around account access and device security.
What this trend says about mobile life is that the phone is becoming less like a tool we consult and more like a keyring we carry. It unlocks services, proves reservations, stores tickets, and increasingly handles payment. That makes the best utility apps almost invisible: they work at the exact point where a real-world task needs them, then get out of the way. Google Wallet’s appeal comes from this quiet role, not from turning finance into entertainment or asking users to spend time inside the app.
The relevance is likely to last, even if the feature list keeps changing. Contactless payments are already an established habit in many places, and digital passes are convenient wherever operators support them. Digital identity may expand, but it will do so under local rules and with careful limits, so it should not be treated as a guaranteed near-term replacement for physical ID. Wallet’s durable value is more modest: a familiar home for everyday items that are already becoming digital.
My recommendation is simple: if you use an Android phone, have a supported payment card, and often carry tickets or loyalty cards, try Google Wallet with the items you use most. It is especially worthwhile for people who commute or travel, because those are the situations where a misplaced card or a slow search costs more than a few seconds. Keep a backup for unsupported services and dead-battery days, and do not expect every local provider to be ready. Used with those limits in mind, it is one of the rare utilities whose best feature is the small amount of attention it asks for.